Why Rising Auto Loan Balances Call for Faster, Smarter Underwriting at the Point of Sale
Auto loan balances keep climbing. So does the share of borrowers falling behind. But that headline hides the real story.
Most auto loan defaults aren't a borrower choosing not to pay. They're a borrower who can't pay this month, for reasons that had nothing to do with their intent at signing.
That distinction matters for how auto lending gets underwritten and priced at the point of sale, not just how delinquent accounts get handled later. This piece stays focused on origination and pricing, along with asset financing software built to support it. Collections and early-warning systems are worth their own conversation, elsewhere.
Key Takeaways
- Auto loan balances and delinquencies are both rising, but different measures track different things. Don't blend them into one stat.
- Most defaults trace back to cash flow strain, not intent, which changes what underwriting should screen for.
- Digital underwriting speeds up decisions, but only helps if risk discipline stays just as strong.
- Captive financing is still a real threat. Banks win on speed and digital experience, not by cutting corners on pricing.
- Risk-based pricing still carries real compliance obligations. Speed never removes them.
Where Auto Loan Debt and Delinquency Stand Right Now
A few sources track auto lending health. Each measures something slightly different.
- The New York Fed's Household Debt and Credit Report put auto loan balances at $1.69 trillion in Q1 2026. Its Q2 2026 release flagged elevated new delinquencies for auto loans.
- Fitch Ratings' subprime auto ABS index hit a 32-year high in January 2026. 60-plus-day delinquencies among subprime borrowers reached 6.90 percent, the highest since Fitch's series began in the early 1990s.
- TransUnion's broader consumer-level measure, covering the full credit spectrum rather than only subprime ABS pools, put 60-plus-day auto delinquency near 1.57 percent in Q1 2026, a slow multi-year climb rather than a spike.
- Cox Automotive tracks vehicle repossessions on its insights platform, which estimated 1.73 million repossessions in 2024, the highest count since 2009.
These numbers don't measure the same thing. Blending them into one headline stat would misrepresent what's happening. What they agree on: risk is rising gradually across the market, and much faster within subprime.
Why Auto Loan Defaults Are Usually a Cash Flow Problem, Not Intent
LendingTree's analysis of auto loan defaults found 83.7 percent of defaulted borrowers had deep subprime credit, scores below 580. The average credit score among defaulted accounts was 529.
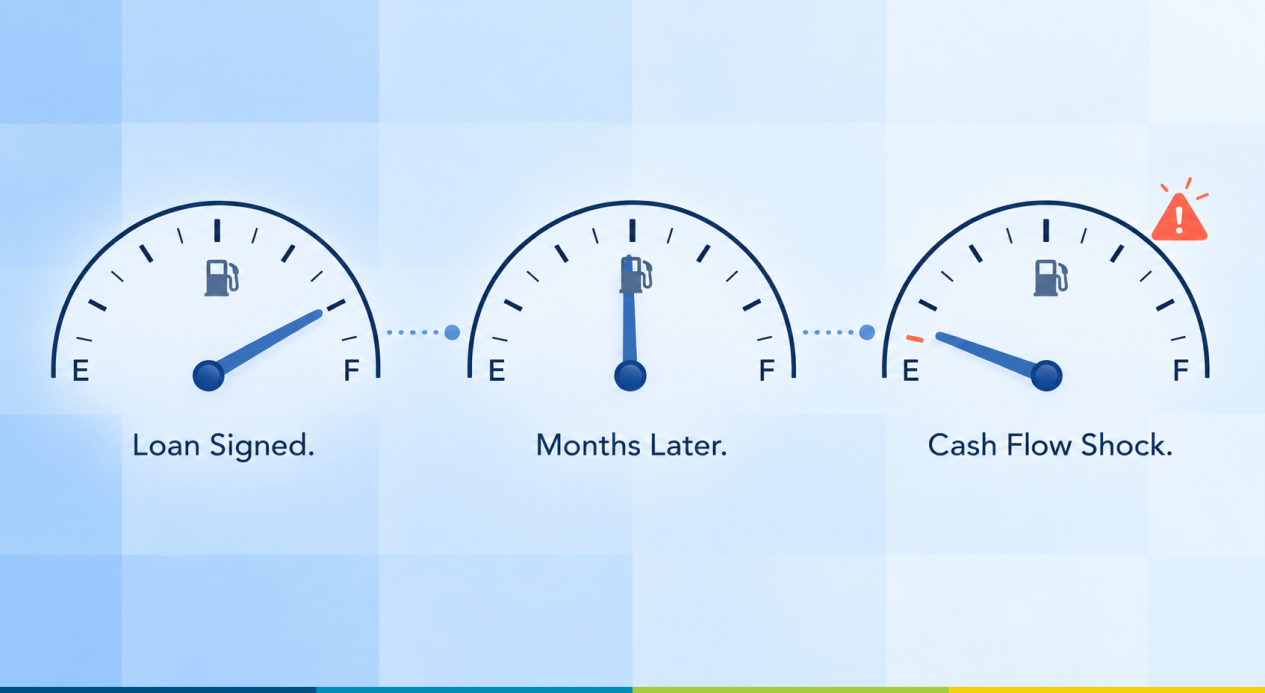
Defaults also happen late. On average, defaults happen 42 months into a 69-month loan, not in the first few months.
That timing says something. A borrower who paid for three and a half years wasn't planning to stop. Something changed. A job loss. A medical bill. A rent increase that ate into the budget. The loan didn't fail because underwriting missed a flag at signing. It failed because a cash flow shock hit a borrower with little cushion.
This reframes the underwriting question. Instead of "does this borrower intend to pay," ask "how much cushion does this borrower actually have if something goes wrong." The related question of how to catch distress in existing loans before it escalates is a separate job. This piece is about getting the math right before the loan is ever booked.
The Role of Digital Underwriting in Vehicle Loan Origination
Point-of-sale auto lending runs on speed. A dealership finance desk needs a decision in minutes, not hours, or the deal walks to a competitor. Digital underwriting meets that need, pulling credit, income, and vehicle data together automatically instead of routing a file through manual review.
Faster doesn't mean looser. The goal isn't approving more deals faster. It's applying the same risk standard every time, without a rushed finance manager skipping a step under pressure.
Rule-based vs AI credit decisioning at scale is what actually makes speed and discipline work together.
Competing With Captive Financing Offers From Manufacturers
Captive lenders, the finance arms of manufacturers, remain a major force. Their market share moves quarter to quarter, though. Experian's State of the Automotive Finance Market report put captives at 26.83 percent of financing in Q1 2026, banks at 28.42 percent, and credit unions at 20.09 percent. Read any single quarter as a snapshot, not a stable fact.
Captives compete on subsidized rates. Banks can rarely match that directly. Where banks can win is digital experience and decision speed, and captives often lag here. J.D. Power's Automotive Finance Digital Experience Study found captive lenders still trailing non-captive bank brands on digital experience, even as the industry improves overall.
That gap is winnable. A bank with strong point-of-sale technology can offer a faster, cleaner experience than a captive, even without matching a subsidized rate. Faster doesn't mean looser applies here too. Winning on speed only works if the underwriting behind it holds.
Risk-Based Pricing at the Point of Sale
Risk-based pricing sets different rates for different risk profiles instead of one flat rate for everyone. Done well, it lets a lender serve a wider range of borrowers profitably. Done carelessly, it creates compliance exposure that has nothing to do with speed.
The FTC and CFPB's Risk-Based Pricing Rule under Regulation V requires a notice when credit is granted on less favorable terms because of a credit report. Denials carry a separate adverse action notice under ECOA and Regulation B. Neither obligation disappears because a decision took ninety seconds instead of two days. Faster doesn't mean looser applies most literally right here.
Modernizing Origination Without Slowing Down Approvals at the Dealership
Lenders modernizing origination often reach for a specialized add-on, a separate tool bolted onto whatever core system already runs the loan book. That works short-term and creates friction later. Across multiple dealerships, a bolt-on point solution means reconciling data between systems that were never built to talk to each other.
The more durable fix is origination technology that handles credit pulls, income verification, and decisioning in one connected flow. The dealership finance desk gets a decision without waiting on a system handoff.
Lenders taking this approach cut turnaround time and eliminate processing delays without loosening the standards behind the decision.
Summary
- Auto loan balances and delinquencies are both climbing, but different sources track different segments. Don't collapse them into one number.
- Most defaults happen well into the loan term and trace back to cash flow shocks, not an intent to avoid payment.
- Digital underwriting and risk-based pricing can genuinely speed up decisions, but speed needs equal or better risk discipline, not less.
- Captive financing remains a real threat. Banks compete best on digital experience and speed, an area where captives still lag.
- Compliance obligations around pricing and adverse action apply no matter how fast the decision gets made.
Auto lending doesn't need to trade speed for discipline at the point of sale. Getting both right starts with underwriting built around how borrowers actually default, not outdated assumptions about intent.
A useful next step is a 10-point readiness checklist for assessing whether your origination stack can keep up.
FAQs
What is auto lending modernization?
Auto lending modernization means upgrading origination, underwriting, and pricing systems to work faster and more consistently, typically by connecting credit, income, and vehicle data into one workflow instead of routing files through manual steps.
How does digital underwriting improve auto loan origination?
Digital underwriting pulls credit, income, and vehicle data together automatically, letting lenders apply consistent rules at dealership speed. It cuts manual error and delay without changing the underlying credit standard.
Why is point-of-sale underwriting important for auto lenders?
Point-of-sale underwriting decides whether a deal closes at the dealership or walks to a competitor. A slow decision loses deals regardless of how sound the underwriting is.
What is risk-based pricing in auto lending?
Risk-based pricing sets loan terms based on a borrower's credit risk instead of one flat rate for everyone. It requires specific notices under Regulation V, and separate adverse action notices apply if credit is denied.
How can lenders compete with captive auto financing?
Lenders compete with captive financing by matching decision speed and digital experience, an area captives often underperform in, rather than trying to match subsidized manufacturer rates directly.