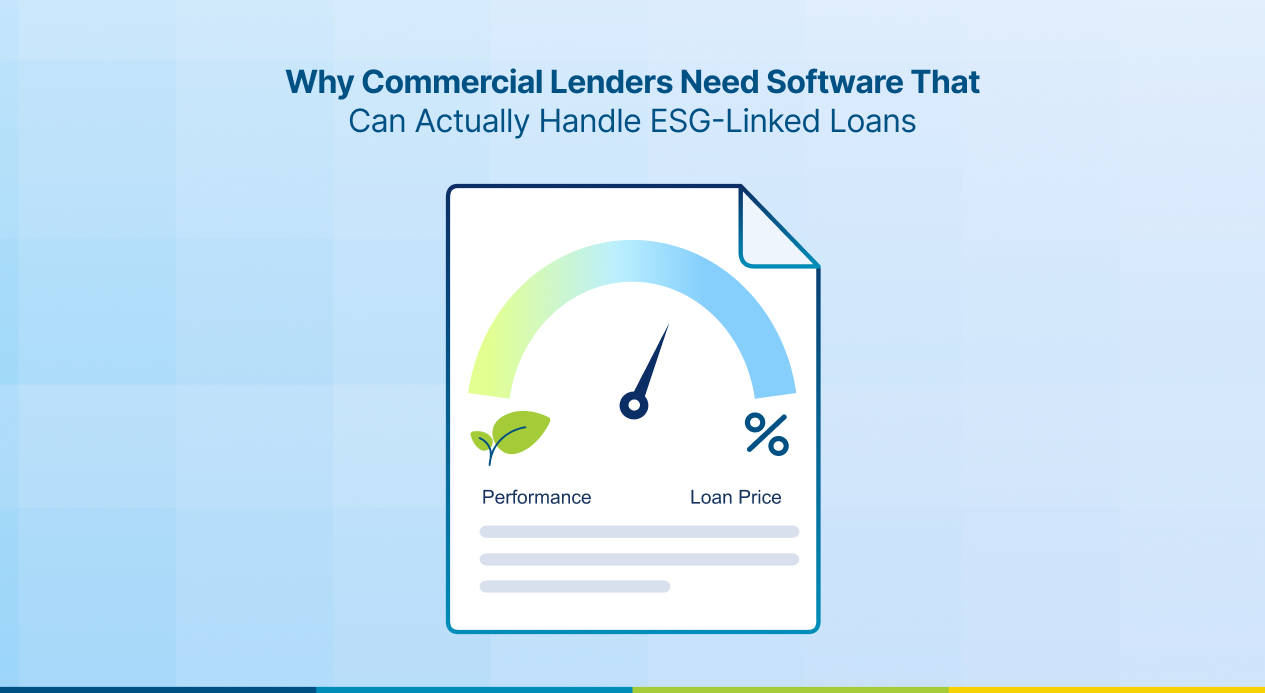
Why Commercial Lenders Need Software That Can Actually Handle ESG-Linked Loans
Sustainability-linked loans aren't in a hype cycle anymore. Issuance grew fast for a few years. Then it cooled down, once regulators and investors started asking harder questions about greenwashing.
The market that's left is smaller, but far more scrutinized. And that scrutiny is exposing something most lenders haven't fully dealt with.
The commercial lending software running commercial credit today wasn't built to track, price, or report on sustainability-linked loans the way the market now expects.
This piece walks through what sustainability-linked loans actually require operationally, where standard commercial lending infrastructure runs into trouble, and what credit and technology leaders should check before this product line grows further on their books.
None of it requires deep ESG expertise to follow. It just requires looking at the mechanics of the product honestly.
Key Takeaways
- Sustainability-linked loans need dynamic, KPI-driven pricing and reporting that most core lending systems were never built for.
- ESG data, emissions figures, diversity ratios, and third-party verification records don't map cleanly onto standard underwriting or covenant fields.
- Weak tracking on sustainability-linked loans creates real disclosure and greenwashing exposure, not just an operational headache.
- Closing this gap rarely requires a new platform or a separate ESG module. It usually means adding this capability to the lending intelligence layer a bank already runs.
- As sustainability-linked loans become a standard part of commercial credit, the credibility of the underlying data will matter as much as the credit decision itself.
What Sustainability-Linked Lending Actually Means in Practice
The language around ESG-linked credit gets muddled often enough that a quick reset helps. Three products get mixed up constantly, and they aren't the same thing.
- Green loan. Proceeds are restricted to a specific use, like financing a solar installation or an efficiency retrofit.
- Sustainability-linked loan. Proceeds carry no restriction at all. What moves instead is the price, and it moves based on whether the borrower hits agreed sustainability performance targets, tracked against negotiated KPIs.
- Transition loan. Closer to the green loan model. It finances a borrower's shift toward a lower-carbon business, but it's still a use-of-proceeds structure, not a performance-linked one.
The Loan Syndications and Trading Association frames sustainability-linked loans around four things: alignment with the borrower's sustainability strategy, how targets get set, how performance gets reported, and how that reporting gets reviewed independently. Notice what's missing? Nothing about what the money gets spent on.
That's the real dividing line between an SLL and a green loan. It's also why the two products need to be tracked completely differently once a loan is booked.
For a lender, this distinction decides three things: what data gets captured, how pricing behaves over the life of the loan, and what the credit agreement needs to prove later. Get it wrong, and the systems built to manage the deal end up designed for the wrong product entirely.
That's a big part of why so many sustainability-linked loans still get managed by hand well after closing.
Why ESG Data Doesn't Fit Cleanly Into Standard Underwriting Fields
Underwriting systems were built around numbers that behave in familiar ways. Revenue. DSCR. Leverage ratios. Collateral values.
ESG KPIs don't behave like that. A Scope 1 emissions figure has no natural home in a field built to hold a debt service coverage ratio. A workforce diversity ratio doesn't either. Most loan origination systems have no built-in way to connect an SPT to a margin adjustment mechanism at all.
So the KPI baseline, the SPT trajectory, and the verification records for a sustainability-linked loan usually end up somewhere else entirely. They get tracked in spreadsheets outside the core system, maintained by whoever on the credit team happens to own that relationship.
That works fine until the person managing the spreadsheet moves teams. Or until an auditor asks to see the full KPI history against the credit agreement, in one place, and nobody can pull it together quickly.
Covenant Tracking and Reporting Requirements Specific to ESG Loans
Sustainability-linked loans carry a reporting rhythm standard covenants don't have. On top of the usual financial covenant checks, a lender now has to:
- Track annual KPI performance against the agreed SPT path
- Confirm external verification actually happened on schedule
- Have a clear answer for what happens if that verification is late, incomplete, or disputed
None of this is a one-time check at closing. It runs for the life of the loan, often three to five years. It needs an audit trail showing exactly what KPI data came in, when it arrived, and who verified it.
A system built only to flag a missed payment or a breached financial ratio has no equivalent mechanism for flagging a missed sustainability report. That gap tends to stay hidden until a renewal, an audit, or a regulator forces the question.
Pricing Structures Tied to Sustainability Performance
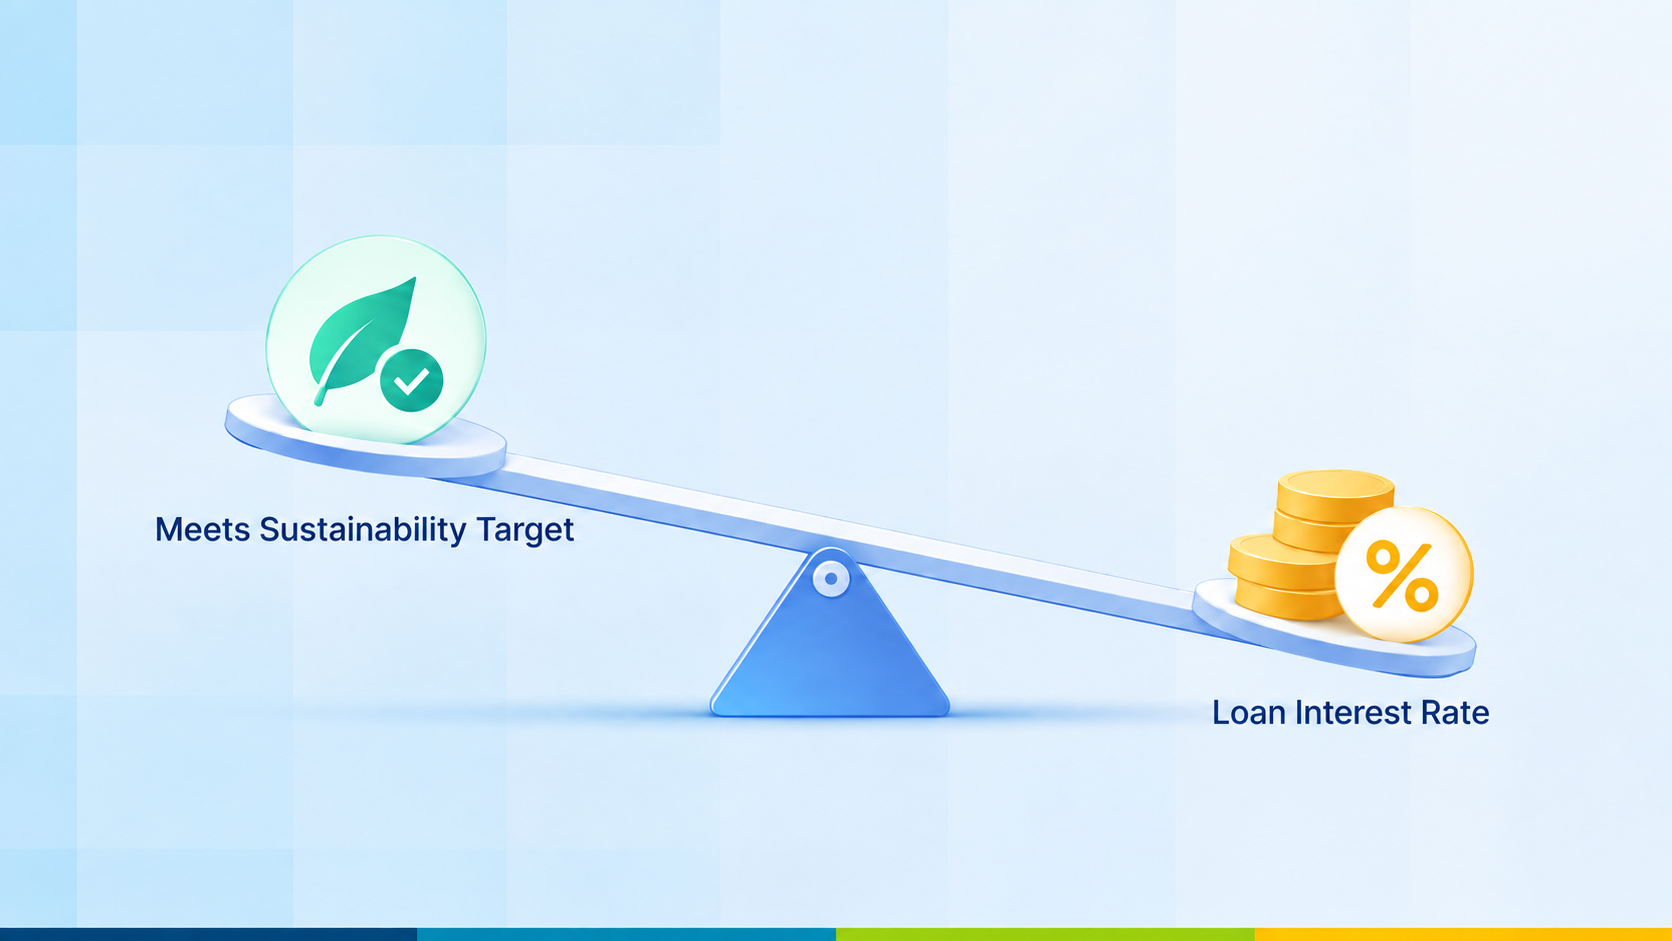
The margin ratchet is what makes a sustainability-linked loan actually work as a product.
- Hit the SPT, and the margin steps down.
- Miss it, and the margin either holds flat or steps up, depending on the facility's structure.
- Some deals route part of that adjustment into a fee paid toward a sustainability project instead of a straight rate penalty.
That's a genuinely different pricing model from a standard commercial facility, where the margin gets fixed at close and only moves through formal amendment. A commercial lending system needs conditional, KPI-triggered repricing built in as a core function, not bolted on as a manual adjustment someone runs once a year.
Here's what that looks like in practice. A mid-market manufacturer takes out a five-year revolving facility, with its margin tied to a 5 percent annual cut in Scope 1 and Scope 2 emissions.
Each year, the lender pulls the verified emissions figure, checks it against the agreed trajectory, applies the right margin adjustment, and logs the calculation with its supporting evidence. Now multiply that across a growing book of sustainability-linked loans, each with its own KPI, its own verification timeline, and its own ratchet formula. A process that works fine for one deal on a spreadsheet stops working at any real scale.
Where Current Commercial Lending Software Falls Short
Most commercial lending platforms were designed for a simpler world: covenants that are financial ratios checked on a fixed schedule, and pricing that stays static between amendments.
That's not a knock on the platforms. It's just not the job they were built for. And to be fair, this isn't a market with zero answers. Some vendors have addressed the gap with a dedicated ESG add-on sold alongside their core platform.
The trouble is what that route demands from the lender running it:
- Separate implementation
- Separate data entry
- A second system that has to be reconciled against the core lending platform instead of living inside it
For a bank with even a modest book of sustainability-linked loans, a bolt-on point solution recreates exactly the kind of fragmentation the rest of the lending stack has spent years trying to eliminate.
Disclosure and Compliance Risk When ESG Commitments Are Tracked Poorly
Regulators stopped treating sustainability-linked loans as a niche product a while back. The European Banking Authority's progress report on greenwashing names lending as one of the areas most exposed to greenwashing risk. The reason is simple: sustainability-linked loan terms get disclosed publicly, while the KPI tracking behind them often stays informal internally.
That gap, between what gets disclosed and what can actually be proven, is where the real exposure sits. A lender reporting a sustainability-linked loan portfolio publicly, but unable to produce a clean audit trail of KPI performance against SPTs on request, is sitting exactly where regulators are now watching.
Two industry bodies underline the same concern. The Loan Market Association has published its own guidance on navigating this risk. The International Capital Market Association has pushed for consistent external review standards across green, social, and sustainability-linked instruments. Both signal how central verification has become to whether these loans hold up under scrutiny.
The exposure only compounds for lenders operating across borders. A policy that looks compliant on paper but fails across jurisdictions creates liability wherever the disclosure rules are strictest.
What Lenders Should Look for in ESG-Ready Lending Infrastructure
Strip away the noise, and the list of capabilities that actually matter here is short:
- Configurable KPI fields. Set per facility, not hardcoded once for everyone.
- A pricing engine built for conditions. It needs to handle KPI-triggered margin adjustments as a native function, not a manual override someone has to remember.
- A real audit trail. Every reported KPI value should link back to its verification source, so a sustainability-linked loan can be substantiated the moment someone asks.
None of that calls for a full platform migration. The more realistic path for most lenders is extending the lending intelligence layer they already run on top of existing origination and servicing systems, adding ESG tracking and pricing capability without disrupting live loan operations.
Whether that capability arrives through a dedicated module or an extension of the platform already in place, the underlying requirement stays the same. Sustainability-linked loans need the same rigor as every other credit obligation on the book.
They shouldn't run as a side project next to the loans that actually flow through the core system.
Summary
- Sustainability-linked loans differ structurally from green loans. They're tied to performance targets, not to how proceeds get used, and that distinction decides what needs tracking.
- ESG KPIs and SPTs don't fit standard underwriting fields, which is exactly why they so often end up managed in spreadsheets outside the system of record.
- Margin ratchets tied to sustainability performance need dynamic, conditional pricing logic that most commercial lending platforms don't support out of the box.
- Weak KPI tracking on sustainability-linked loans is now a documented regulatory focus area, not a hypothetical risk.
- Closing this gap doesn't require a platform migration. It requires ESG tracking and pricing capability layered onto the systems a lender already runs.
Sustainability-linked lending isn't a passing trend in commercial credit anymore, and the volume of sustainability-linked loans on lenders' books is only going to grow from here.
How credible that book stays, for lenders, borrowers, and regulators alike, depends on whether the systems behind these facilities can back up what's written into the credit agreement. Is your lending stack ready for this? That's worth answering before the next sustainability-linked loan closes, not after.
FAQs
What is a sustainability-linked loan?
A sustainability-linked loan is a credit facility where pricing moves based on whether the borrower hits predefined sustainability performance targets, tracked through agreed KPIs. It places no restriction on how the loan proceeds are used.
How is a sustainability-linked loan different from a green loan?
A green loan restricts how proceeds are used, typically financing a specific environmental project. A sustainability-linked loan places no such restriction. Its margin moves up or down based on the borrower's performance against sustainability targets instead.
Why do sustainability-linked loans create challenges for lending software?
They require tracking non-financial KPIs, applying conditional margin adjustments tied to performance, and managing recurring external verification. None of that fits the financial-ratio-based covenant fields, or static pricing logic most commercial lending systems were built around.
What happens if a borrower misses its sustainability performance target?
Depending on how the facility is structured, missing an SPT usually means the margin holds flat or steps up. Some structures instead require the borrower to pay a fee toward a sustainability initiative rather than a straight rate increase.
Do lenders need new software to offer sustainability-linked loans?
Not necessarily a new platform. Most lenders can add ESG covenant tracking and KPI-based pricing capability to the lending infrastructure they already run, rather than migrating systems or adopting a standalone bolt-on tool.